Employers: Share This with Your Team — There’s Still Time to Max Out 401(k) and HSAContributions in 2026
Last Updated on September 10, 2026 by Pamela Chowdhury
With only a few months left in the year, now is the time to remind your employees about an
incredible opportunity to reduce their tax burden and build long-term wealth.
Here’s what your team needs to know:
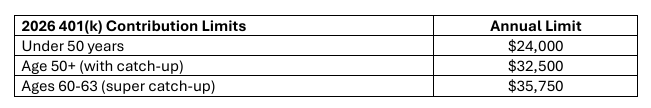
Deadline: Contributions must come from payroll by December 31, 2026. That means
employees need to adjust their payroll deferrals now to spread the increase across
remaining paychecks.
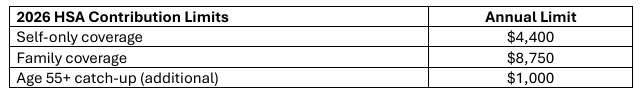
Deadline: HSA contributions can be made until April 15, 2027, but encouraging
employees to contribute through payroll (pre-FICA tax!) before year-end maximizes savings.
Why does this matter?
- 401(k) contributions lower taxable income dollar-for-dollar and grow tax-deferred.
- HSAs are triple tax-advantaged. Contributions are tax-deductible, growth is tax-free, and
withdrawals for qualified medical expenses are tax-free. No other account offers all three. - The new “super catch-up” for employees ages 60–63 is brand new under SECURE 2.0.
Many employees don’t even know it exists yet. If you have team members in that age range,
a quick heads-up could mean an extra $11,250 sheltered from taxes this year.
What should you do as an employer?
- Send a reminder to all employees about current limits and how to adjust their
payroll deferrals. - Highlight the super catch-up — it’s new and widely overlooked.
- Encourage HSA payroll contributions over direct contributions to capture FICA tax
savings. - Connect employees with your benefits administrator or accountant if they need
help running the numbers.
The end of the year comes fast. A simple reminder today could make a meaningful
difference in your employees’ financial futures.
Questions about how to communicate this to your team? Reach out — we’re happy to help.